

Expense IQ Money Manager

- 2.81K Reviews
- 3.2
- Downloads
- 1,000,000+
Our take on Expense IQ Money Manager from Appgk
I came away from Expense IQ Money Manager with a fairly clear impression: it is a practical, hands-on finance app for people who want to understand where their money goes, but it asks for more personal discipline than the simplest modern banking tools. I like it most as a daily spending journal and planning workspace, not as a completely automatic financial assistant.
That distinction matters. The app combines expense tracking, budgeting and bill reminders in one place, which makes it useful when I want a single view of regular household money. At the same time, the experience depends heavily on keeping entries accurate and maintaining the system over time. If I am willing to record purchases consistently, the structure is valuable. If I expect the app to do nearly everything for me, it can feel like work.
How Expense IQ works in everyday money management
Expense IQ is a free finance app from Handy Apps, and it has been available since May 14, 2014. Its long presence helps explain the overall design: this feels like a mature utility built around organizing information rather than a flashy budgeting experiment. The current version is 2.3.2, and it supports devices running Android 4.4 or later.
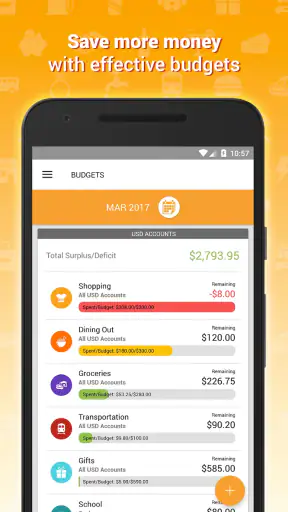
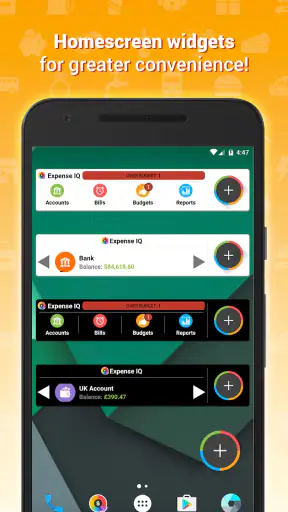
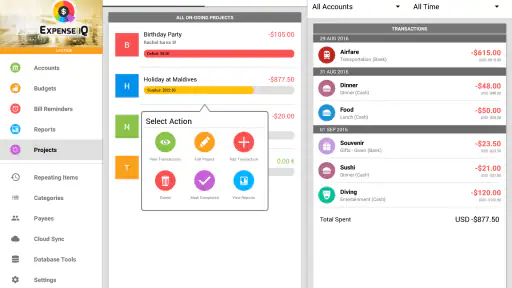
When I use it as intended, I think of the app in three layers. First, I record what I spend. Second, I compare those transactions with a budget. Third, I use reminders to keep upcoming bills from disappearing into the background. Those jobs are closely related, but they answer different questions: where did my money go, how much room do I have left, and what payment is approaching?
Best Parts of Expense IQ Money Manager
Things to Keep in Mind About Expense IQ Money Manager
The expense journal is the foundation. A useful entry is more than a number because it gives the later budget view some meaning. Recording a supermarket purchase under the right type of spending is more helpful than leaving it as an unexplained withdrawal. I found that the app becomes increasingly useful when I use consistent categories instead of creating a new label for every unusual purchase.
That consistency is one of the less obvious skills needed to get good results. For example, I would not split one month’s food purchases between “groceries,” “market,” and “household food” unless I had a specific reason. A tidy category structure makes later review much easier. It also prevents a misleading sense that I am under budget simply because similar purchases were scattered across several labels.
News and Features Related to Expense IQ Money Manager

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
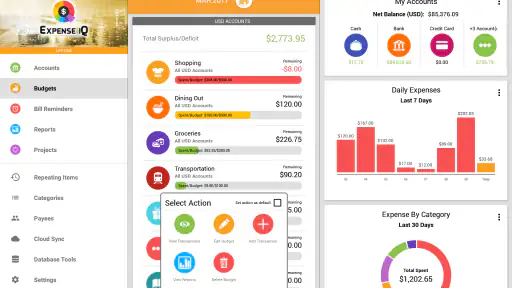
The budget planner is most helpful when I treat it as a limit-setting tool rather than a prediction machine. Before a month begins, I can think through recurring obligations and flexible spending. During the month, the important question is not just the total amount spent, but whether the remaining amount is realistic for the days still ahead. That makes the app more useful for course correction than for looking back with regret.
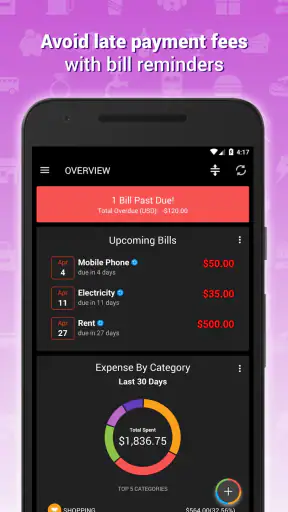
Bill reminders add a different kind of protection. I see them as a separate layer from ordinary spending because a rent payment, subscription or utility bill can be expected even when I have not yet paid it. A reminder does not solve a cash-flow problem by itself, but it can stop an avoidable missed payment from being caused by forgetfulness. The practical tip is to enter a bill when I first think about its due date, not when I am already worried about it.
Don't want to read the full review?
A realistic routine would be a weekly household check-in. On a quiet evening, I could enter the week’s card purchases, review the categories that grew faster than expected, and look at bills coming soon. That takes more intention than opening a banking app, but it gives me a clearer explanation of my behavior. If eating out has quietly replaced grocery spending, the pattern becomes visible before the end of the month.
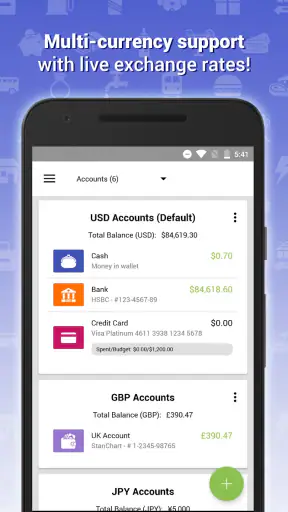
For someone managing more than one account or spending source, the value comes from seeing the household picture together. A person might use one account for everyday purchases, another for fixed payments and cash for small expenses. Keeping those streams organized can make a monthly review more meaningful than checking each account separately. The trade-off is that every stream must be maintained carefully; an incomplete record is worse than a simple record that is consistently updated.
Screenshots
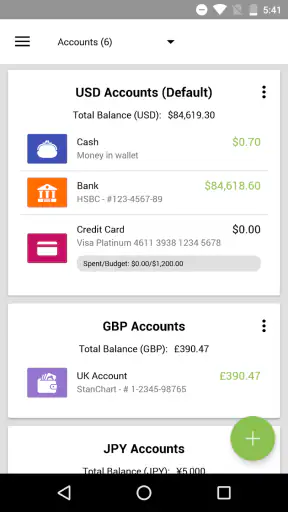
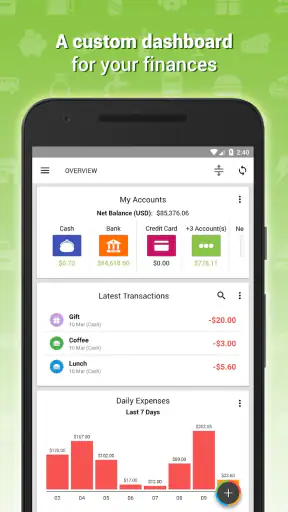
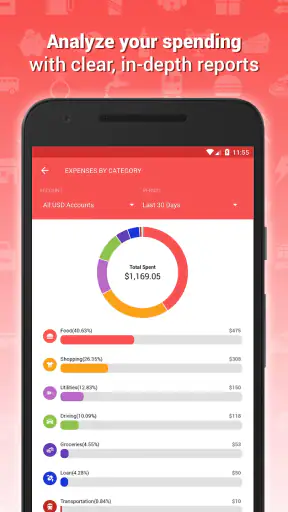
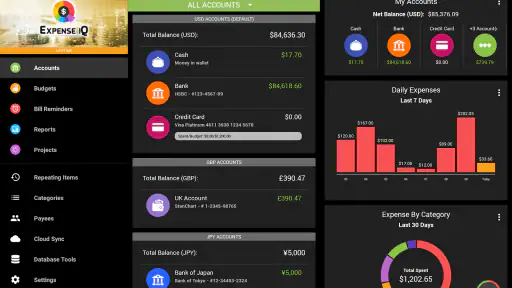
I also appreciate that this approach encourages active awareness. Many financial apps emphasize instant totals, but a manual entry can make a purchase feel more memorable. That is not always convenient, yet it can be useful for people who are trying to change habits. The act of classifying a purchase creates a small pause between spending and forgetting.
The strongest part is the connection between records, limits and reminders
The best reason to choose this app is the way its main tools support one another. A spending record on its own is descriptive. A budget on its own is an intention. A bill reminder on its own is a prompt. Together, they create a simple routine for planning, recording and checking.
I would especially recommend setting up the system around fixed commitments first. Regular bills should be accounted for before I decide how much flexible money is available for transport, meals, entertainment or shopping. This order prevents a common mistake: treating all money in an account as available simply because a future payment has not been deducted yet.
There is another useful trade-off here. A highly detailed budget can look impressive but become tiring to maintain. I get better results by starting with a small number of meaningful groups, then adding detail only when a category is causing trouble. If transport is always predictable, it may not need several subcategories. If food spending is the problem, more detail there may be worthwhile.
The app also suits a review habit rather than a one-time setup. I would not judge it after entering a few transactions on the first day. Its real value appears after enough ordinary spending has been recorded to reveal patterns. That makes it a better fit for someone who wants an ongoing money-management practice than for someone seeking a quick financial snapshot.
Its broad adoption suggests that this style of money management has found a substantial audience. Expense IQ has passed one million installs, with an average rating of 3.2 from around twenty-three thousand ratings and roughly two thousand eight hundred written reviews. I read that combination as a sign of a useful but not universally loved tool: many people find a purpose for it, while others likely struggle with the effort or the interface.
The app is free to install, which makes experimenting with its workflow relatively easy. However, in-app purchases range from around four dollars to about one hundred twenty-five dollars per item. I would therefore look carefully at which parts of the experience I actually need before paying for anything. The free starting point is helpful, but the possible purchase range means the overall cost should be considered rather than assumed.
Where the manual approach becomes a real weakness
The central limitation is not a minor inconvenience: the quality of the results depends on the quality of the entries. If I forget several purchases, enter them late or categorize them inconsistently, the budget picture becomes unreliable. The app can organize what I give it, but it cannot make an incomplete financial diary accurate.
That can be frustrating during busy weeks. A person who uses several payment methods may return to the app with a pile of transactions to reconstruct. At that point, the process feels less like a helpful habit and more like administrative work. I would rather record a purchase soon after making it than attempt a large catch-up session, especially when small cash expenses are easy to overlook.
This also affects the app’s suitability for people who expect seamless automation from their financial tools. A bank application may be more convenient for checking balances and recent transactions, while a modern automated budgeting service may reduce manual entry. Those alternatives can be better when speed and automatic updating matter more than personal categorization.
On the other hand, an ordinary banking app often does not provide the same deliberate planning experience. Bank transaction lists are excellent for confirming what happened, but they may not encourage me to assign a future limit or think through upcoming bills. Expense IQ is stronger when I want to make spending decisions before the money disappears, provided I accept the responsibility of maintaining the record.
Privacy expectations are another reason to choose carefully between tools. I would personally avoid entering sensitive notes that are unnecessary for budgeting. The safest workflow is to keep entries focused on useful financial information and protect access to the device itself. I would also review the app’s current permissions and privacy details before making it the main record of household finances, especially if my needs are more demanding than basic tracking.
The age rating is Everyone, which makes the app broadly approachable from a content perspective. That does not mean every child or teenager will find it suitable as a personal finance system. Younger users may need help deciding categories, understanding recurring bills and interpreting a budget. For an adult teaching basic money habits, however, the straightforward tracking concept could provide a practical starting point.
I would skip Expense IQ if I want investment analysis, tax preparation, detailed shared-account collaboration or a fully automated connection to every financial provider. Those needs call for specialized services. I would also skip it if I know I will not record purchases regularly. In that situation, a simpler balance-checking routine may be more honest and more sustainable than maintaining a detailed budget that quickly becomes outdated.
Who will get the most from it
The best audience is someone who wants control without needing a complicated financial platform. A student learning to manage a monthly allowance, a couple organizing household bills, or a worker trying to understand irregular discretionary spending could all benefit. The common thread is a willingness to participate in the process rather than handing every decision to automation.
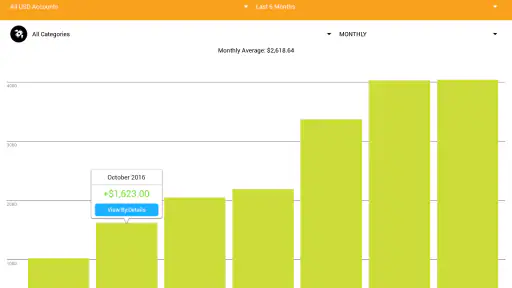
It is particularly useful for people whose problem is not a lack of financial information but a lack of structure. If I already know my account balance yet still wonder where the money went, recording categories and setting limits can expose the gap between intention and behavior. That is a more useful insight than simply seeing a lower balance at the end of the month.
For couples or families, I would agree on category names and an update routine before relying on the totals. One person recording restaurant spending as “food” and another recording it as “entertainment” can make the shared picture confusing. A short weekly review is more valuable than arguing over numbers later, and the app works best when everyone follows the same method.
People with irregular income can use it, but they should budget conservatively. I would base essential commitments on money that is genuinely available, then treat better-than-expected income as a reason to adjust later rather than spend in advance. The app can help display that plan, but it cannot remove the uncertainty of freelance work, seasonal income or variable hours.
It is also a reasonable choice for someone moving away from paper notes. A paper notebook can be flexible, but it is easy to lose totals and harder to review consistently. A bank statement is more automatic, but it may not reflect the personal categories that matter to me. Expense IQ sits between those options: more organized than handwritten notes, more intentional than a raw transaction feed.
The main question is whether I want a budgeting tool or merely a financial dashboard. If I want to be prompted to think, categorize and plan, this app has a sensible role. If I want to open an app and immediately receive a complete, automatically updated analysis, I would look elsewhere. Neither preference is wrong; they simply lead to different tools.
My verdict after weighing convenience against control
Expense IQ Money Manager earns my recommendation for disciplined users who want expense tracking, budget planning and bill reminders in one focused finance app. Its strongest quality is the relationship between those functions: I can record a purchase, measure it against a plan and remember what is due next. That combination gives everyday spending more context than a basic account screen.
My recommendation comes with a clear condition: use it consistently and keep the setup manageable. Start with essential categories, enter bills early, review the week before it becomes a month, and avoid adding detail that does not change a decision. Those habits do more for the experience than building an elaborate budget that is abandoned after a few days.
The average rating of 3.2 shows that the app is not a universal solution, and my own view is similarly balanced. It is not the smoothest choice for people who prioritize automation, nor is it the right tool for advanced financial analysis. Its value is quieter and more practical: it gives willing users a place to turn scattered spending into a routine they can actually inspect.
For me, the final test is simple. If I am prepared to spend a few minutes keeping the record current, the app can help me make better everyday choices and avoid forgetting recurring obligations. If I am not prepared to do that, I would choose a more automatic alternative instead. Expense IQ is best understood as a hands-on money habit, not a magic financial answer.
Expense IQ Money Manager FAQ
What is Expense IQ Money Manager used for?
Expense IQ Money Manager is a personal finance app designed to help you track spending, organize income and expenses, manage budgets, and monitor your overall financial habits. During use, transactions can be grouped into categories, while reports and summaries make it easier to understand where your money goes. It is suitable for everyday budgeting, household finances, and basic expense planning.
Does Expense IQ Money Manager support budgets, bill reminders, and recurring transactions?
Yes, the app is built around practical budgeting tools rather than simple transaction recording. You can create spending limits for different categories, schedule recurring income or expenses, and set reminders for upcoming bills. These features are useful for users who want to avoid missed payments and compare their actual spending with the budget they planned for the month.
Can I use Expense IQ Money Manager for multiple accounts and currencies?
Expense IQ Money Manager can be useful for people who separate finances across cash, bank accounts, credit cards, or other wallets. Depending on the version and device configuration, account and currency options may vary, so it is worth checking the current app listing before downloading. Users with international finances should confirm supported currencies and exchange-rate features in advance.
Is my financial information safe in Expense IQ Money Manager?
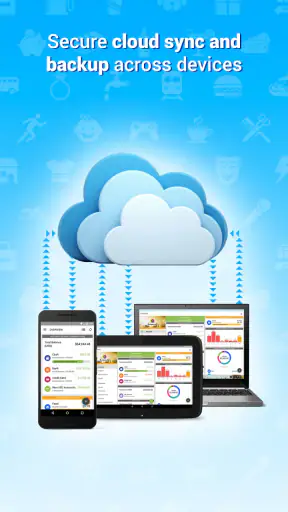
Because the app handles sensitive financial information, privacy and security should be considered before entering detailed data. Expense IQ Money Manager may provide protection options such as an app password or similar access controls, but these should not be treated as a replacement for device security. Review the current privacy policy, backup settings, and data-sharing practices before relying on it for important records.
Is Expense IQ Money Manager free, and are there any limitations?
Expense IQ Money Manager may be available as a free download, but some advanced tools can depend on the edition, subscription, or in-app purchase options offered in your region. Potential limitations may involve advertising, report features, synchronization, backup, or premium budgeting functions. Before installing, check the official Google Play or App Store page for the latest pricing and feature details.











